
Best Financial Freedom Tips for 2026
Hey! Want to break free from money stress? You can start today with a few smart moves. In this short guide you’ll see eight usable tips that can boost your cash flow, shrink debt, and set you on a path to true financial freedom. Let’s start.
1. Automated Savings Apps , Hands‑Free Wealth Building
Automation takes the guesswork out of saving. You set a rule, and the app does the rest. It’s like a silent partner that nudges money into your future every time you spend.
Fidelity explains that automated savings turns good intentions into real results. By rounding up purchases or moving a fixed amount each payday, you can grow a nest egg without thinking about it. Read the Fidelity guide on why automation works. This habit also lets you donate spare change to causes you care about, blending saving with giving.
Imagine you buy a coffee for $4.25 and the app rounds up to $5, tucking the extra 75 cents into a savings bucket. Do that a few times a week and you’ll see a few dollars add up each month.
Choosing the right app matters. Look for low fees, instant transfers, and strong security. Some popular choices let you set multiple goals, travel, emergency fund, or a down payment, so each dollar knows its purpose.
Automation frees up mental space. Instead of worrying about “did I save enough?”, you trust the system. That confidence can spill over into other areas, like investing or negotiating a raise.
Our own coaching program shows how a simple automated habit can be the first step toward larger financial goals. Read how we help home‑based entrepreneurs set up automated savings and keep the momentum going.
2. Low‑Cost Index Funds , Simple Market Exposure
Index funds let you own a slice of the whole market. You don’t pick individual stocks; you buy the basket that tracks a broad index.
Because they simply follow the market, expenses stay low. Over time low fees mean more of your money stays invested and compounds.
According to Wikipedia’s entry on index funds, the average expense ratio for a well‑known S&P 500 index fund is under 0.05 %. That’s a fraction of what actively managed funds charge.
To get started, open a brokerage account and look for funds that track the total market or a major index. Many brokers let you buy fractional shares, so you can start with as little as $10.
Pick a fund that matches your risk tolerance. A total‑stock market fund suits growth‑focused savers, while a balanced fund adds bonds for stability.
Once you’ve chosen a fund, set up an automatic monthly contribution. Treat it like a bill you must pay.
Our network‑marketing community often uses index funds to build a steady, passive income stream. See how the guide ties index investing to residual income.
3. High‑Yield Savings Accounts , Maximize Cash Returns
When you keep cash in a regular checking account, you earn almost nothing. High‑yield savings accounts pay rates that are several times higher than the national average.
These accounts are offered by online banks that have lower overhead. They often provide easy access, FDIC insurance, and no monthly fees.
For the official definition and history, check Wikipedia’s page on savings accounts. It notes that high‑yield accounts typically offer 3‑5 % APY in 2026, compared to the sub‑0.5 % you’d find at a brick‑and‑mortar bank.
To choose the right one, compare interest rates, minimum balance requirements, and how quickly you can transfer money to a linked checking account.
Put your emergency fund here first. It stays liquid, but you still earn a decent return.
Remember to keep enough in your checking for day‑to‑day bills, then funnel the rest into the high‑yield account.
“The best time to let your cash work for you is right now, not later.”
Our coaching program often advises members to park short‑term cash in a high‑yield account before moving money into longer‑term investments.
4. Side‑Hustle Platforms , Boost Income Streams
Extra income can fast‑track your path to financial freedom. The right platform lets you monetize a skill without huge startup costs.
Freelance writing, graphic design, tutoring, and coding are all in demand. Platforms like Upwork, Fiverr, and Tutor.com connect you with clients worldwide.
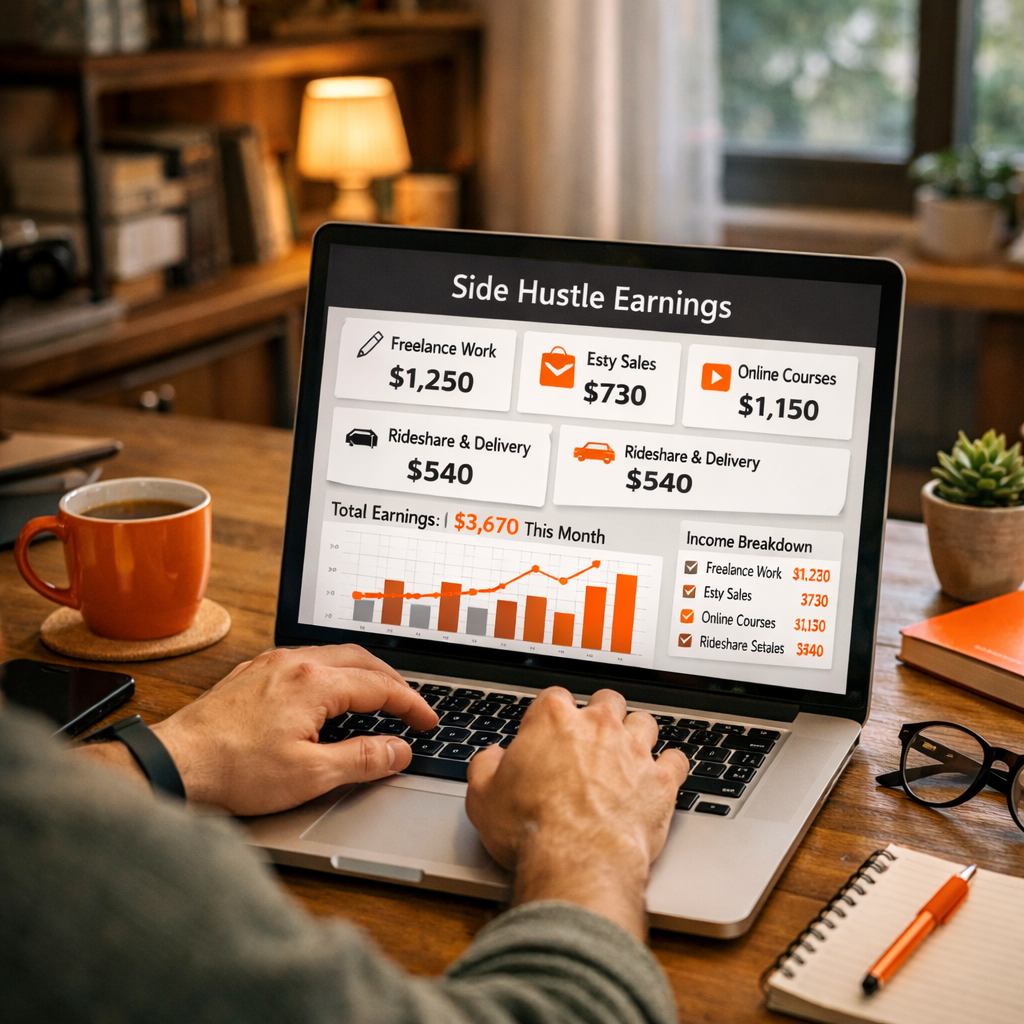
When you pick a platform, check the fee structure, payment schedule, and the type of jobs posted. Some sites take a higher commission but offer higher‑paying clients; others keep fees low but have more competition.
To keep your side hustle from eating up your free time, set a weekly hour cap. Treat the income as a supplement, not a replacement, until you see consistent results.
After each payout, automatically move the money into your investment account or high‑yield savings account. That way the extra cash fuels growth, not spending.
Our network‑marketing mentors often recommend side‑hustles that complement their main business, like creating video content or running webinars. Read how residual income can amplify side‑hustle earnings.
5. Debt‑Snowball Calculators , Accelerate Debt Payoff
Debt can feel like a heavy weight. The snowball method lets you chip away at it one piece at a time, building momentum.
Start by listing all debts from the smallest balance to the largest. Pay the minimum on each, then throw any extra cash at the smallest balance.
When that debt disappears, roll its payment into the next smallest balance. Your payment amount grows like a snowball rolling downhill.
Financial Mentor’s free calculator lets you input balances, rates, and extra payment amounts. It then shows how long it will take and how much interest you’ll save.
Research from ChooseFI shows that while the snowball may cost a bit more interest than the avalanche method, the early wins boost motivation and improve completion rates.
To get the most out of the method, keep your lifestyle modest while you pay down debt. The money you save on discretionary spending becomes extra snowball fuel.
Once all consumer debt is cleared, you’ll have a cash flow surplus. Direct that surplus into investing or a high‑yield savings account to keep the wealth‑building cycle moving.
FAQ
What is the easiest way to start automating my savings?
Begin with a small, fixed amount that feels comfortable, say $25 each payday. Link your checking account to a savings app, set the rule, and let the app move the money automatically. Adjust the amount upward as you get used to the habit, and watch your balance grow without thinking about it.
How do I pick the right index fund for my risk level?
Look at the fund’s asset mix. A total‑stock market fund leans toward growth and suits a higher risk tolerance. A balanced fund adds bonds, lowering volatility. Check the expense ratio, lower is better. Use a brokerage that offers low‑cost, no‑minimum funds to keep costs down.
Are high‑yield savings accounts safe?
Yes, as long as the bank is FDIC‑insured. The insurance protects deposits up to $250,000 per account holder. Choose an online bank with a solid reputation, read reviews, and verify the FDIC coverage on the bank’s website before opening an account.
What side‑hustle should I try if I have limited time?
Pick a skill you already have, like writing short articles, tutoring a subject you know, or doing simple graphic design. Platforms such as Fiverr let you set micro‑gigs that take 1‑2 hours a week. Automate payment transfers so the earnings flow straight into your savings.
How does the debt‑snowball method differ from the avalanche method?
The snowball focuses on the smallest balances first, giving quick wins that boost morale. The avalanche attacks the highest‑interest debt first, saving more on interest. If you need motivation to stay on track, the snowball is often more effective despite a slightly higher interest cost.
Can I combine these tips for faster financial freedom?
Absolutely. Automate a portion of each paycheck into a high‑yield savings account, invest the rest in low‑cost index funds, and use any side‑hustle earnings to accelerate your debt snowball. The synergy of multiple streams speeds up progress and keeps you motivated.
Ready to take the next step? Explore our guide on creating financial and time freedom with MLM for deeper strategies that tie all these tips together.
By putting these habits into practice, you’ll see your money work harder for you. The road to financial freedom isn’t a sprint; it’s a series of small, steady actions. Keep at it, and the results will follow.


