
5 Financial Independence Strategies for Early Retirement
Want to break free from the 9‑to‑5 grind? Most people think early retirement is a pipe dream, but the right steps can make it real. In this guide we walk you through five financial independence strategies that let you save more, earn passive income, and cut costs so you can retire on your terms. By the end you’ll have a clear plan you can start today.
Step 1: Define Your Financial Independence Number
Before you can hit any target, you need a number to aim at. Your financial independence number (FIN) is the amount of after‑tax assets you must own to cover your living expenses without a paycheck. Start by listing every monthly cost , rent, groceries, utilities, insurance, and a little extra for fun. Multiply that total by 12 to get an annual figure.
Next, decide on a safe withdrawal rate. The classic 4% rule suggests you can pull 4% of your portfolio each year and keep the principal safe. If you need $40,000 a year, you’d need $1,000,000 in assets (40,000 ÷ 0.04). Some experts now recommend a 5% rate for today’s market, which lowers the target a bit. Use the rate that feels comfortable for your risk tolerance.
Write your FIN down and put it somewhere you’ll see it every day. A sticky note on your laptop works. Seeing the number keeps you focused and helps you measure progress.
Key Takeaway: Your FIN is a specific goal that turns vague wishes into a measurable target.
Now that you know the number, you can map out how much you need to save each month to hit it. If you have $200,000 saved and need $1,000,000, you still need $800,000. At a 7% annual return, saving $1,500 a month will get you there in about 25 years. Adjust the monthly savings amount until the timeline fits your desired retirement age.
Remember, the FIN isn’t set in stone. Life changes, and you can recalc it each year. The important part is that you have a baseline to work toward.
Step 2: Maximize Your Savings Rate
Saving a larger slice of your income speeds up the path to financial independence. The first habit to adopt is paying yourself first. As soon as your paycheck lands, move a set percentage into a high‑yield savings or investment account before you spend on anything else.
Many early‑retirees aim for a 50% savings rate. That sounds steep, but you can get there by cutting discretionary spending and boosting income. Look at your budget line by line. Do you really need three streaming services? Can you downsize your car or move to a cheaper apartment? Small cuts add up fast.
Boosting income works just as well. Pick up freelance gigs, sell a skill on a marketplace, or start a side hustle that aligns with your passions. Even a modest $200 extra each month can shave years off your timeline.
Track your progress with a simple spreadsheet. List income, expenses, and the amount saved each month. Seeing the numbers rise gives a dopamine hit that fuels the habit.
Automation is your friend. Set up automatic transfers to your retirement accounts and investment platforms. Once the money moves on its own, you’re less likely to miss it and spend it.
For network‑marketing entrepreneurs, The Ultimate Guide to Creating Massive Success in Network Marketing offers a deep dive on how to turn your side hustle into a reliable income stream, helping you raise that savings rate without sacrificing lifestyle.
By consistently increasing the percentage you save, you’ll see compound interest work faster. The magic of compounding means that a higher savings rate not only adds more money but also earns more on the larger base.
Step 3: Invest in Income‑Generating Assets
Saving alone won’t get you to retirement; you need assets that produce cash flow. Common choices include dividend‑paying stocks, real‑estate investment trusts (REITs), rental properties, and digital products. Each has its own risk profile and effort level.
Start with dividend stocks. Look for companies with a history of stable payouts and low payout ratios. A safe bet is a diversified index fund that tracks high‑quality dividend payers. This gives you exposure without picking individual winners.
Real estate can be a solid cash‑flow engine. If you own a home, consider renting out a spare room or converting a basement into a unit. For larger investments, REITs let you own a slice of commercial property without the headaches of landlord duties.
Digital assets like e‑books, online courses, or affiliate sites can generate passive income after the upfront work. The key is to create something that solves a problem for a niche audience.
Some experts’ experience shows the shift from growth stocks to income‑producing assets as retirement nears. They note that rental income, REITs, and dividend stocks became the core of their portfolio once they hit their target. They also point out that a diversified mix helps smooth out market volatility.
Here’s a quick checklist to evaluate an asset:
- Cash‑flow potential , does it generate monthly income?
- Liquidity , can you sell it if you need cash?
- Risk , how volatile is the return?
- Effort , how much time does it require to maintain?
Allocate a portion of your savings to each category based on your risk tolerance. A common split is 40% dividend stocks, 30% REITs, 20% real‑estate, and 10% digital products. Adjust as you age; shift toward lower‑risk, higher‑cash‑flow assets as retirement approaches.
Remember to reinvest any earnings you don’t need for living expenses. Reinvested dividends compound faster, shrinking the time needed to reach your FIN.
Step 4: Reduce Expenses and Optimize Lifestyle
Every dollar you keep is a dollar that works for you. Trimming costs doesn’t mean living miserably; it means being smart about where your money goes.
Start with a zero‑based budget. Assign every dollar a job , rent, groceries, savings, fun , so nothing slips through the cracks. Track your spending for a month with an app or a simple spreadsheet.
Housing is often the biggest expense. If you can downsize, get a roommate, or move to a lower‑cost area, you’ll free up a large chunk of cash. The same logic applies to transportation , an older, reliable car can be cheaper than a brand‑new model.
Food costs can be cut by meal‑planning and cooking at home. Bulk‑buy staples, use discount grocery apps, and avoid eating out more than a few times a month.
A financial guide outlines a five‑step money‑management plan that includes budgeting, tax awareness, and emergency fund building. Their guide stresses the importance of paying yourself first and keeping discretionary spending low a guide to financial independence. Follow those steps to stay on track.
Minimalism can help you see where you’re over‑spending. Declutter your home, sell items you never use, and focus on experiences over things. A simpler life often leads to lower bills and a clearer mind.
Use the money you save to boost your investment accounts. Even a $100 monthly reduction can shave years off your retirement timeline when invested wisely.
One final tip: renegotiate recurring contracts. Call your cable, internet, or insurance providers and ask for a better rate. You’d be surprised how often a simple request leads to savings.
Step 5: Diversify Income Streams
Relying on a single paycheck is risky. Adding multiple income streams builds resilience and speeds up wealth accumulation.
Start with a side hustle that uses your existing skills. If you’re good at writing, freelance on platforms. If you have a knack for teaching, create an online course. The goal is to earn extra cash that you can immediately funnel into investments.
Network marketing can be a powerful engine for residual income. Shush Arya’s coaching program helps home‑based entrepreneurs set up systems that generate ongoing commissions. For a deeper look, see Create Financial And Time Freedom With MLM. The program covers mindset, lead generation, and automation, all of which boost long‑term cash flow.
Another avenue is dividend‑focused investing. Build a portfolio of high‑yield stocks that pay quarterly checks. Reinvest the dividends until you need the cash for living expenses.
Real‑estate crowdfunding platforms let you own a slice of property without being a landlord. These platforms often require lower minimums than buying a whole house, making them accessible for new investors.
Don’t forget digital assets. An e‑book or a niche blog can keep earning money years after you publish it. The key is to create something valuable that solves a problem.
When you combine several streams, a dip in one area won’t cripple your overall cash flow. It also gives you flexibility to quit a job earlier if you choose.
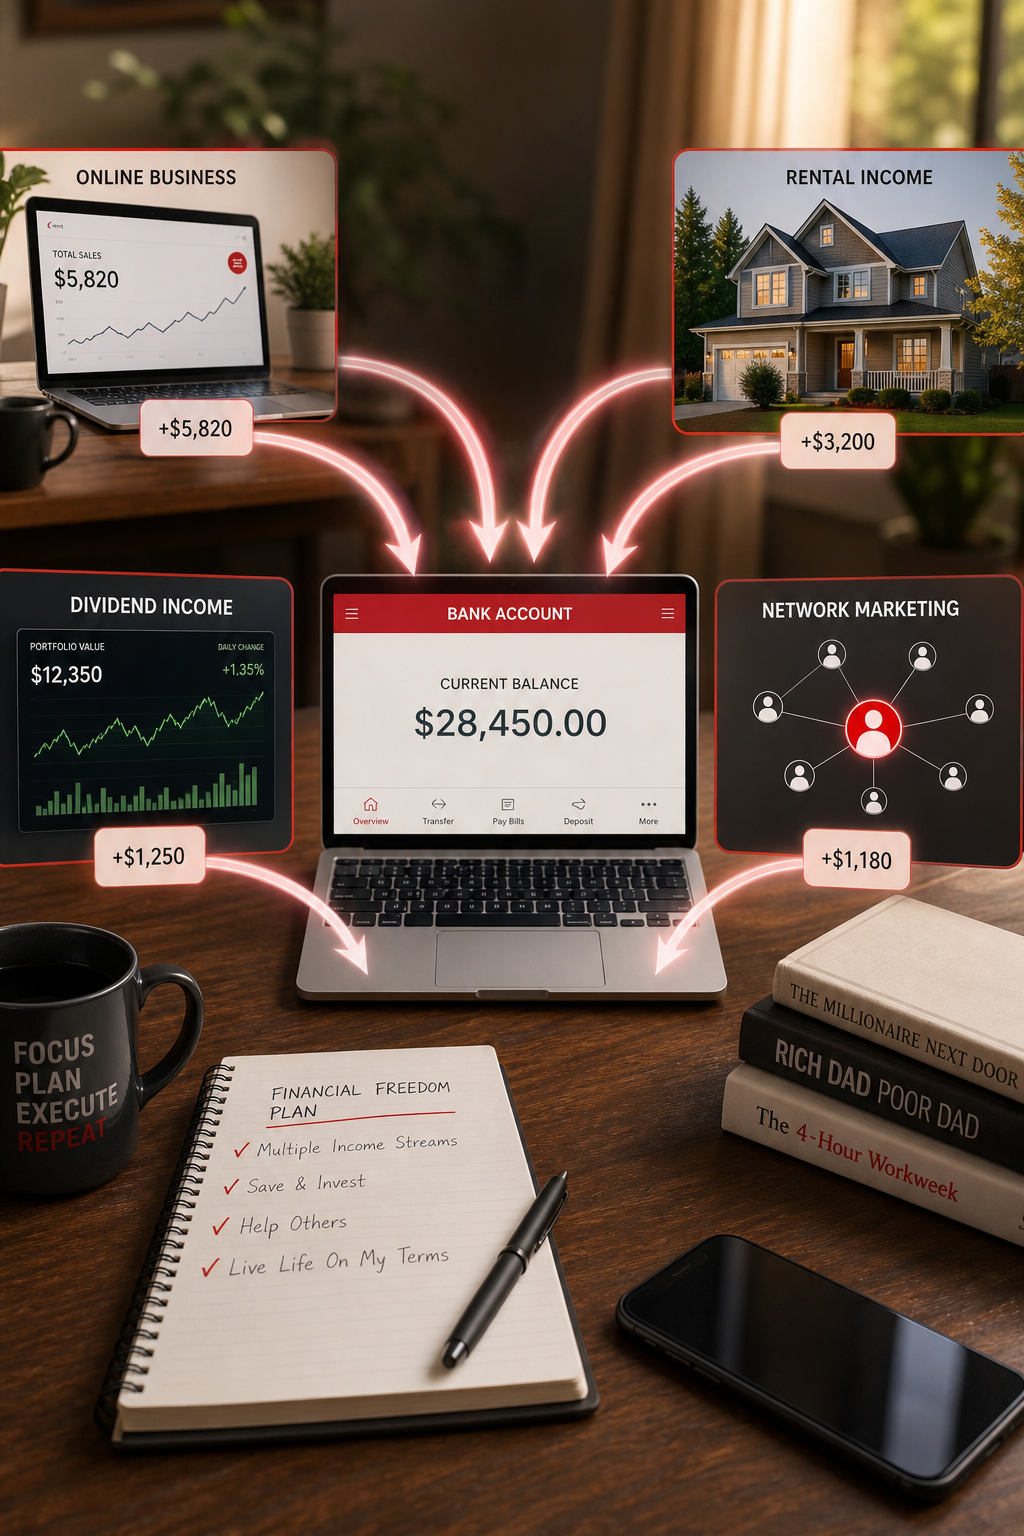
Keep a simple tracker to monitor each stream’s performance. Review quarterly and reallocate money from low‑performing sources to higher‑yield ones.
Frequently Asked Questions
What is a realistic savings rate for someone in their 30s?
Aiming for 30‑40% of after‑tax income is a solid target for most 30‑year‑olds. If you have high debt, start by paying that down while still saving 10‑15%. Once debts shrink, shift more money into savings and investments. The exact rate depends on your lifestyle, but the higher you can push it, the faster you’ll reach your financial independence number.
How long does it usually take to reach early retirement?
Time varies based on income, savings rate, and investment returns. With a 50% savings rate and a 7% annual return, many hit their FIN in 20‑25 years. Those who save 70% can cut that to 15‑18 years. The key is to start early, stay consistent, and adjust as life changes.
Are dividend stocks safe for early retirees?
Dividend stocks can be safe if you pick companies with a long history of stable payouts and low payout ratios. Diversify across sectors to avoid industry‑specific shocks. Pair dividends with other cash‑flow assets like REITs and rental income to balance risk.
What role does mindset play in achieving financial independence?
Mindset drives consistency. Viewing savings as “paying yourself first” and treating investments as a habit rather than a gamble helps you stay the course. Coaching programs that focus on mindset, such as Shush Arya’s mentorship, can reinforce these habits and keep motivation high.
Can I retire early without a large initial capital?
Yes, if you keep your expenses low, save aggressively, and invest wisely. Strategies like minimalism, side hustles, and high‑yield investments let you build wealth from modest beginnings. The key is to avoid lifestyle inflation and keep reinvesting earnings.
How often should I review my financial independence plan?
Review your plan at least twice a year. Check that your savings rate, investment allocations, and expense tracking are on target. Adjust for life events, new job, marriage, kids, and re‑calculate your FIN to stay aligned with your retirement timeline.
Reaching early retirement isn’t magic; it’s a series of deliberate steps. Start by defining a clear financial independence number, then push your savings rate, invest in cash‑flow assets, trim unnecessary costs, and build multiple income streams. As you put each strategy into practice, you’ll watch your net worth climb and your freedom grow.
If you want to dive deeper into the concepts behind financial independence, check out Wikipedia’s definition of financial independence for a solid overview.
Ready to take the next step? Explore more guides on building residual income and learning the mindset needed for lasting wealth. The journey starts now, and every small action moves you closer to the life you deserve.


